SS-4
EIN application · December 2025
Prepare Form SS-4 to apply for an Employer Identification Number (EIN). Enter the applicant’s details, review the official PDF and download your application to complete under the IRS instructions.
Preparing the official PDF. You can start filling below.
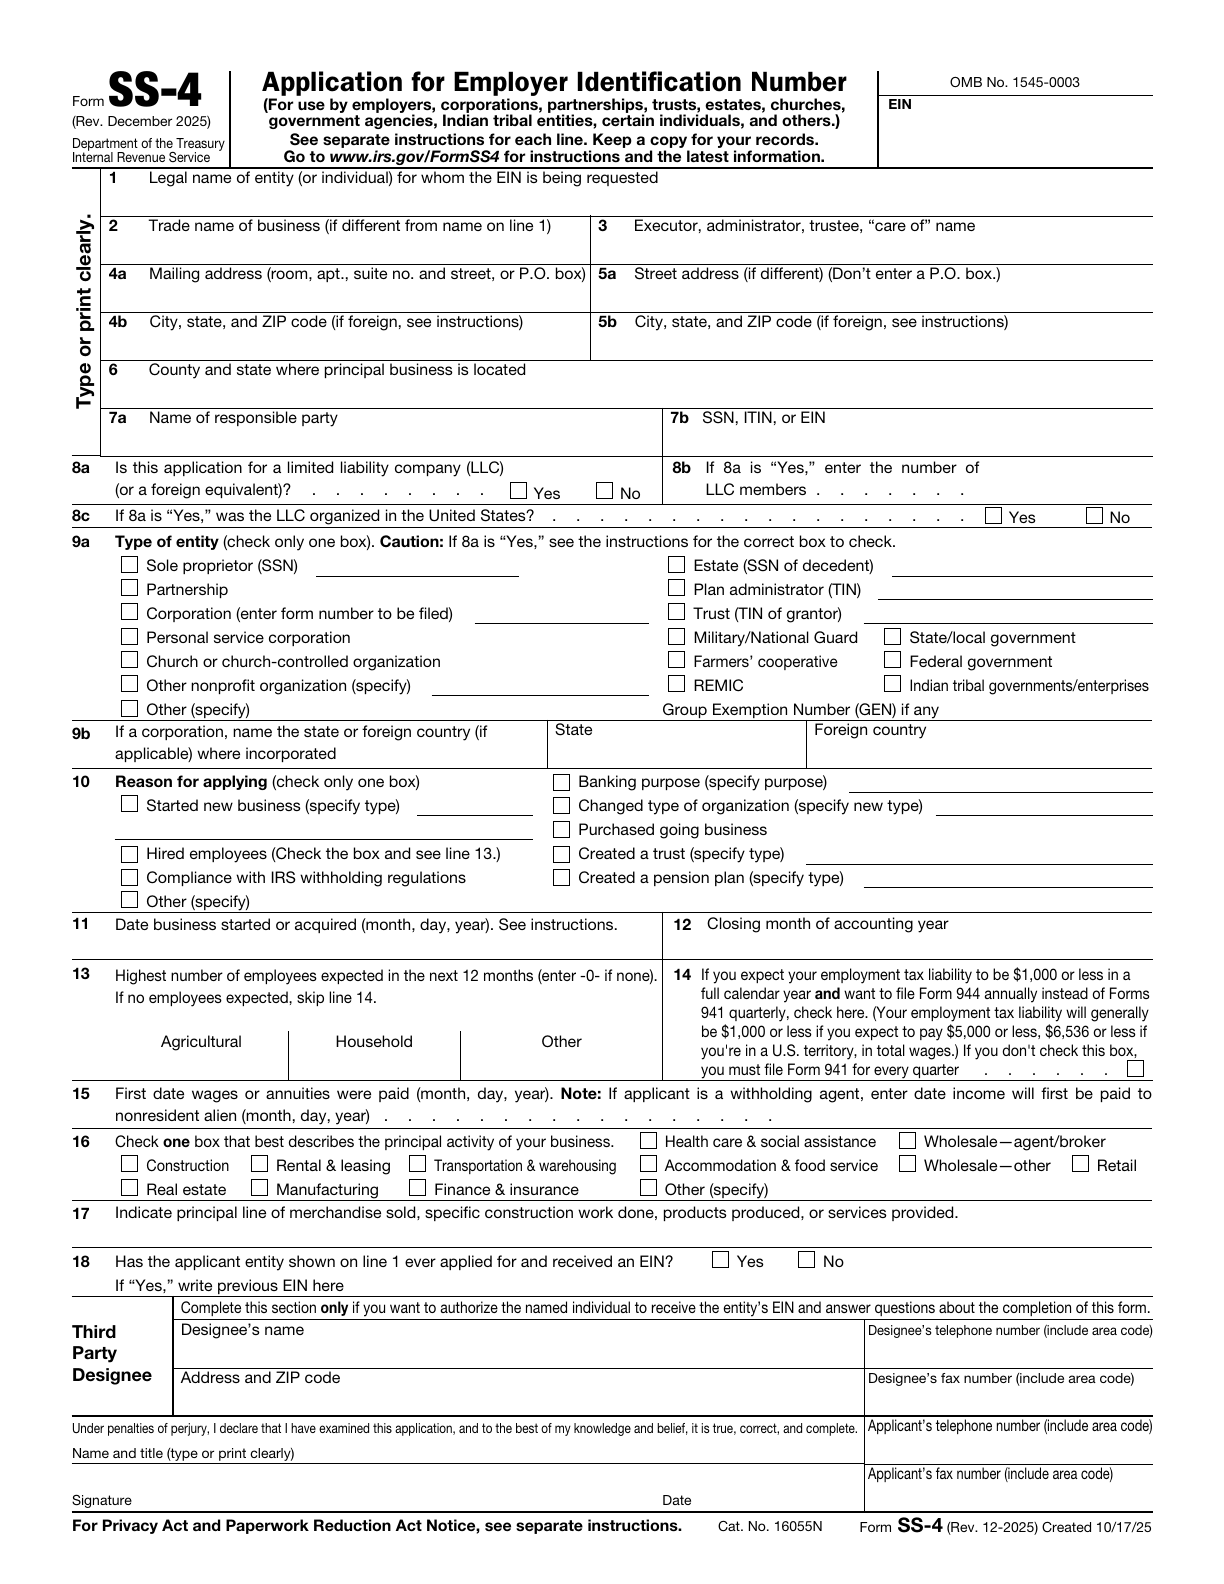
Source: IRS · SS-4 · December 2025 · Official blank PDF
What to have ready Have the applicant’s legal name, mailing and physical addresses, responsible party’s name and permitted TIN, LLC and tax-classification details, reason for applying, accounting month, employee plans and any prior EIN ready. If applicable, gather trustee/executor details and third-party designee authorization. Read the official page 2 matrix and complete instructions before deciding which lines apply.
Find the decisions behind each SS-4 line
Use the official first page to connect the applicant, responsible party, entity type and reason for applying. Page 2 explains which lines your situation requires.
Start with the business and the person in control
Gather the applicant’s legal details and identify who ultimately owns or controls it. Those answers explain different parts of an EIN application.
Illustrative small-business preparation scene.Who is applying, who controls it, and who assigns the EIN?
The person with ultimate ownership or effective control; line 7 records the relevant name and TIN.
Assigns the applicant’s EIN through the official application process.
The business, entity or sole proprietor named on line 1 that is applying for an EIN.
A sole proprietor may be both the applicant and the responsible party. Except for government entities, the responsible party must be an individual; government and permitted foreign/N/A TIN exceptions follow the official instructions. Preparing or downloading SS-4 does not assign an EIN.
An optional third-party designee is a separate role: authorization permits answering SS-4 questions and receiving the EIN until it is assigned and released. It does not automatically make the designee the responsible party or a continuing tax representative.
Line 18 records a previously issued EIN. The top-right box is only for an EIN the IRS has already assigned to this application; leave it blank when no number has been assigned.
Find these questions on the official SS-4
This detail is from the official English original. Labels identify locations and do not change the original form.
1Lines 1–6 · Applicant and addresses
Use the legal applicant’s name and a complete mailing address. Add lines 5a–5b only for a different street address, with no P.O. box. County on line 6 means the principal location’s county, not country.
2Lines 7a–7b · Responsible party
Identify who ultimately owns or controls the entity. Except for government entities, use an individual and their SSN or ITIN. The foreign / N/A exception applies only when that individual has neither number and cannot obtain one.
3Lines 8–9 · LLC and tax classification
LLC status and federal tax classification are separate. Answer the LLC questions, then select the correct line 9a type and applicable explanation. Do not assume every single-member or foreign LLC has the same classification.
4Lines 10–18 · Purpose and business plans
Choose one reason and use page 2 to decide which business, employee and activity lines apply. Zero employees is an answer, not a blank. A withholding agent may need a first payment date even with no employees. Review any prior EIN before applying again.
5Signature area · Complete after download
The applicant name-and-title field does not sign the form. After downloading, review the authorized signer rules and complete the signature and date under the official filing instructions.
SS-4 prepares an EIN application. A completed download is neither an assigned EIN nor an IRS submission. Leave the top-right EIN blank unless the IRS has already assigned it for this application.
Check the official page 2 line-requirements matrixResolve the responsible-party and LLC questions first
These choices describe different facts. A registered agent, a legal LLC and its federal tax classification are not interchangeable. Use the official instructions for your circumstances.
- Responsible party ≠ nominee
- For most entities, name the individual with ultimate control over funds and assets. Government entities may use a responsible-party EIN. Foreign or N/A is restricted to individuals with no SSN/ITIN who are ineligible for both; it is not a substitute for an unavailable number.
- Domestic LLC · members and elections matter
- A domestic single-member LLC accepting default disregarded treatment selects Other and enters Disregarded entity. A domestic LLC with two or more members generally defaults to Partnership. An LLC that elects corporate treatment uses Corporation and its actual return number; a single-member entity also includes Single-member. Filing SS-4 does not make an 8832 or 2553 election.
- Foreign LLC · liability also matters
- Foreign default rules depend on both member count and liability. Two or more members with at least one without limited liability generally default to Partnership; all members with limited liability generally default to Corporation; one owner without limited liability generally defaults to disregarded status. Check eligibility and any actual election in the official instructions.
- Other and special entities need precise descriptions
- Other is not N/A. Use the applicable type and return description. The state/local government household employer agent is a specific exception: both Other and State/local government are checked, with Household employer agent entered. A nonprofit EIN alone does not confer exemption, and a four-digit GEN is different from an EIN.
The editor records your choices; it does not determine tax status or make an election. U.S. disregarded entities wholly owned by foreign persons may need the specific Form 5472 descriptions on both lines 9a and 10. Read the complete instructions before choosing.
Read the official form and all instructionsReview both pages, sign and choose the IRS filing channel
The download contains all 2 pages of the official SS-4. Review your entries on page 1, consult the line-requirements matrix on page 2 and complete the required signature and date after downloading. Follow the applicable IRS filing instructions. FormAgile does not submit the application or assign an EIN.
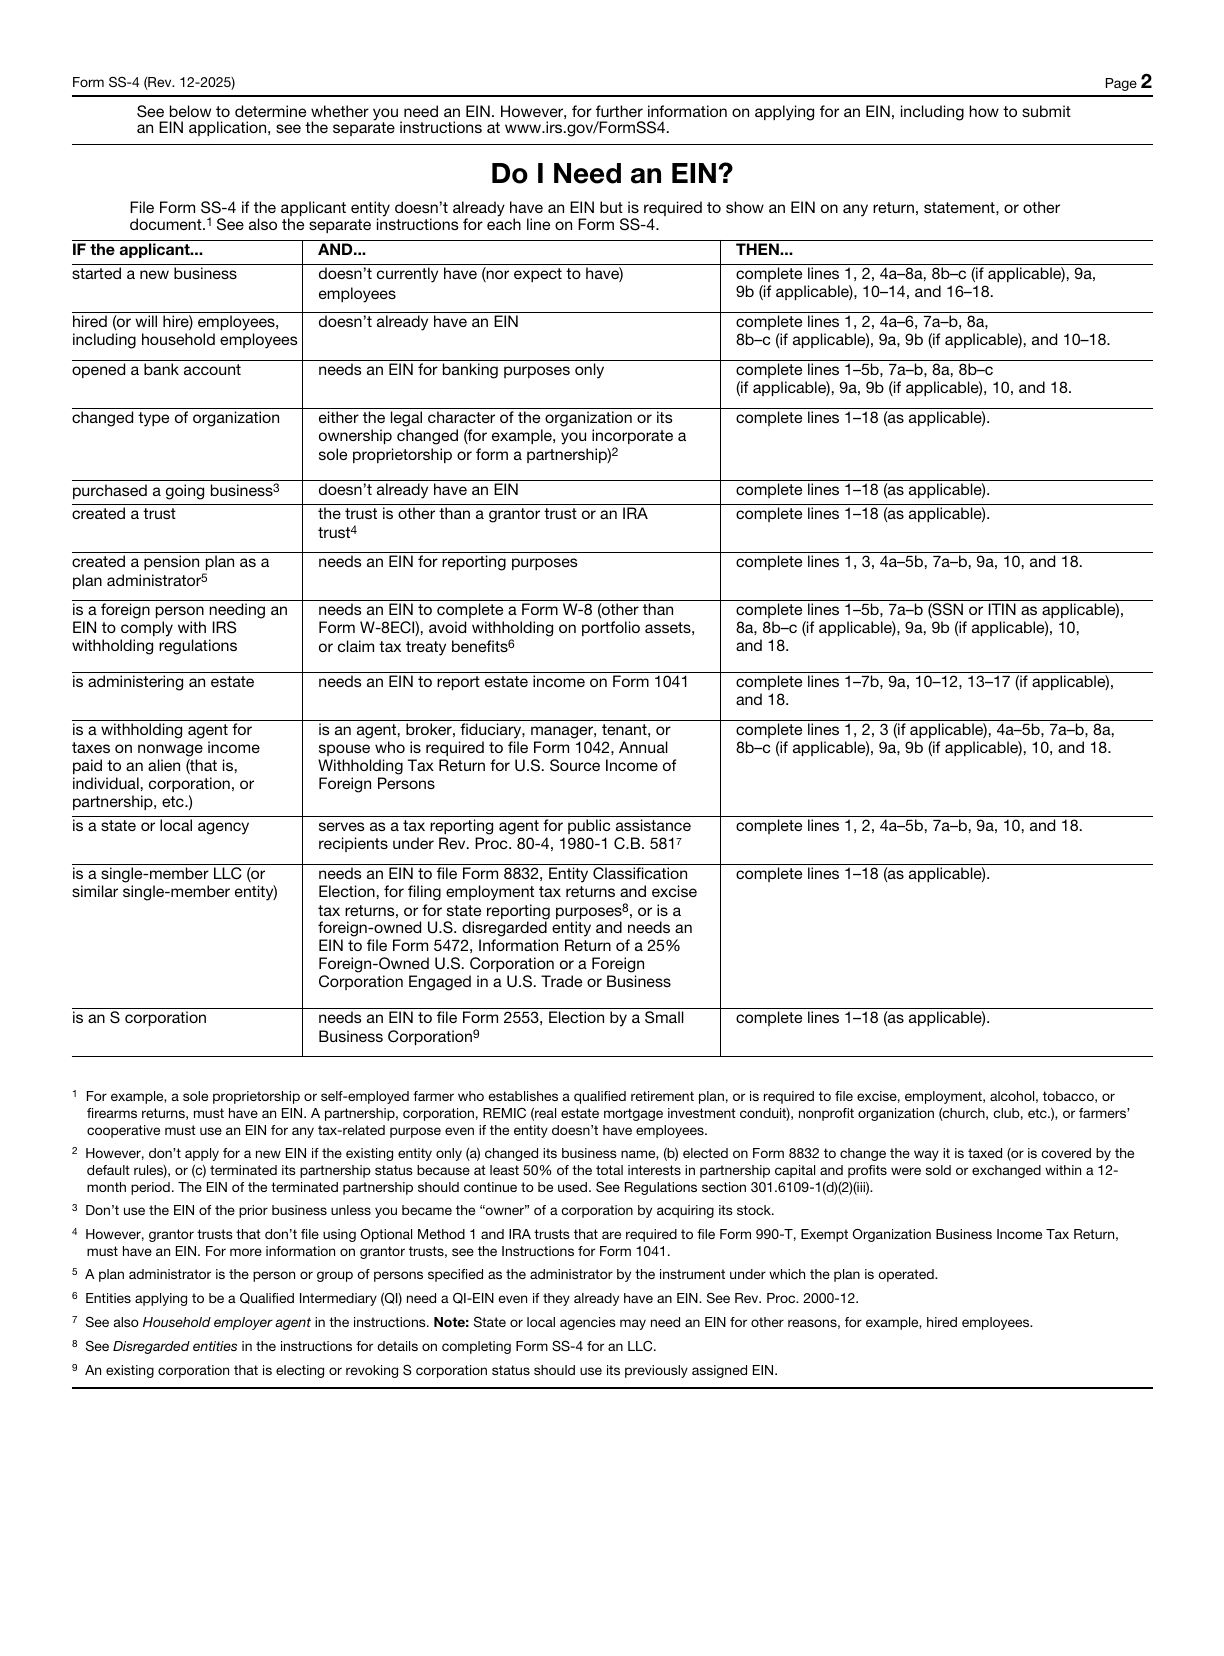
Download includes all 2 original pages
The download includes the complete official original. Page 1 contains your entries; page 2 retains the official line-requirements matrix and notes.
1 · Review the applicant and applicable lines
Confirm names, responsible-party details, entity classification and any previous EIN. Use the page 2 matrix to check which lines apply. The download preserves both pages; it does not split them automatically.
2 · Complete an authorized signature and date
Follow the official signature rules: the individual applicant, a corporation’s principal officer, a knowledgeable authorized member or officer, or the trust/estate fiduciary as applicable. Foreign applicants follow the duly authorized person rule. Third-party designee authorization also requires a valid signature.
3 · Follow the appropriate IRS application instructions
Use the IRS channel that applies to your location and circumstances. International applicants may use the instructed phone, fax or mail route. If a designee’s address or phone matches the applicant’s, use mail or fax. Check current destination details in the official instructions.
This PDF is unsigned and has not been submitted. FormAgile does not assign an EIN. Read the current IRS instructions for filing addresses, fax numbers, international phone applications and signature requirements. Do not apply through more than one method for the same EIN.
View the original PDFSpecial situations and tool limits
Do I need to complete every line?
Use the official page 2 matrix for your purpose. Banking-only and certain withholding or pension-plan administrator applications need fewer lines; ordinary business applications need more. A field can remain editable even when optional. Enter explicit zeros when employee counts apply, and use a first payment date for a withholding agent when the line 15 instructions require it.
Read the official form and all instructionsDoes a trust or plan administrator always need a new EIN?
Not always. Certain grantor trusts may use the grantor/owner’s name and TIN under the official reporting method; other trust situations require a separate EIN. A plan administrator that already has an EIN generally uses that number. When a new pension-plan trust needs an EIN, the instructions direct applicants to the Created a pension plan reason rather than Created a trust. Check the complete trust and plan exceptions before applying.
Read the official form and all instructionsWhat does a foreign-owned U.S. disregarded entity enter for Form 5472?
Under the specific Form 5472 instructions, select Other on line 9a and enter Foreign-owned U.S. disregarded entity-Form 5472. On line 10, select Other and enter Foreign-owned U.S. disregarded entity filing Form 5472. These are different explanations for different lines. This describes a U.S. entity owned by a foreign person, not every entity formed abroad. Check your actual filing circumstances in the official instructions.
Read the official form and all instructionsWhat if the applicant already has an EIN?
Check whether a new EIN is actually required. A name or address change, new employees or a corporate tax election alone generally uses the existing EIN. A new legal structure or ownership change can require a new one, with specific exceptions. Complete line 18 accurately and consult the IRS guidance before reapplying. Downloading a prepared SS-4 does not assign a number or submit another application.
Read the official form and all instructionsHow are my entries handled?
Your entries are processed in this browser page. Each form keeps its own draft during site navigation; refreshing or closing the page clears the drafts. Optional analytics, including Clarity recordings, follow your choice in Analytics settings and the Privacy Policy. Download a copy to keep your work.
Can I edit the downloaded PDF?
Yes. The exported PDF preserves all 2 original pages and editable fields. It is unsigned. Follow the recipient’s signing and delivery requirements.
Why might some text need review?
The original PDF has limited field space. If text cannot fit or its characters are unsupported by the PDF font, we will identify the field so you can revise it. We never silently remove characters or clip overflowing content.
Use the official SS-4 form and instructions
This guide is tied to the December 2025 original. Read the full IRS instructions for entity exceptions, application methods and current destination details.
SS-4 · December 2025
FormAgile is an independent service, not affiliated with the IRS or any government agency. Official blank forms are available free from the IRS. This tool does not provide tax or legal advice.