706 or 706-NA: decedent details
Complete the separate decedent name and personal-number boxes. Keep your own identifying details on line 3; Form 706 instructions use 8822 for an executor’s address change.
Home mailing address · February 2021
Tell the IRS about a new home mailing address for individual, gift, estate or generation-skipping transfer tax returns. Review the people and addresses involved, then download the official two-page Form 8822 for signing and mailing.
Preparing the official PDF. You can start filling below.
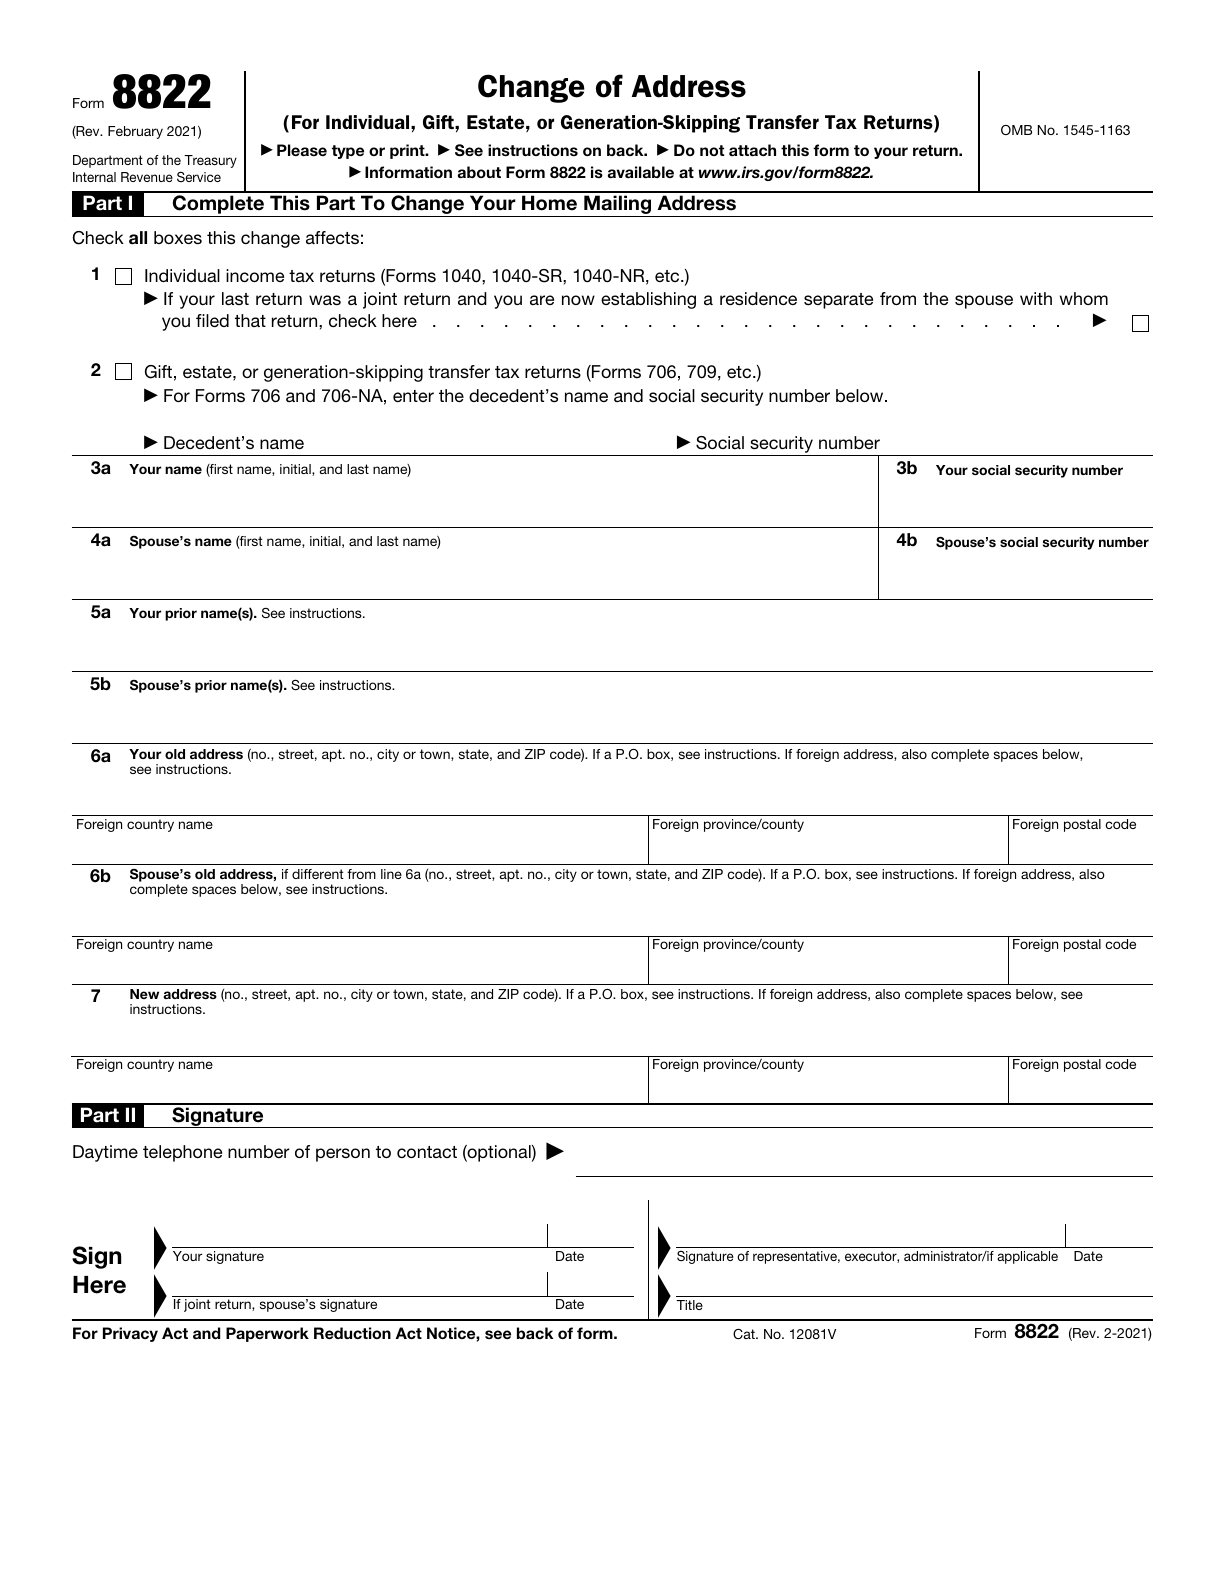
Source: IRS · 8822 · February 2021 · Official blank PDF
What to have ready Have your name and personal tax number, old and new mailing addresses, and any applicable spouse, prior-name or decedent details ready. A signing representative needs a copy of the power of attorney.
Start with the affected returns, then distinguish a shared move from separate residences. Form 8822 covers home mailing records; business changes use 8822-B.
Keep the previous IRS record beside the new address, and decide which people this update covers.
Choose the facts that apply. The editor does not determine marital status, tax liability or signing authority.
Explore these examples independently of your entries.
This is an explanation, not an extra filing. The current download prepares one unsigned Form 8822; it does not update another person’s address automatically.
A child who filed their own income tax return needs a separate Form 8822 for their address change.
The separate-residence box records a specific change after a joint return. It is not a general marital-status declaration.
Line 6a identifies your old record. Line 6b is only a different old record for your spouse. Line 7 is the new mailing address.
For a foreign address, use the complete country name and the local postal format. Province or county and postal code may be blank where not applicable.
For mail received through another person, include C/O and their name with the address. Receiving mail does not authorize someone to sign.
Include apartment, room or suite details. Use a P.O. box instead of the street only when the post office does not deliver there.
Use the address previously recorded with the IRS, including any applicable foreign-address boxes.
Complete only when their old address differs from line 6a. When it was the same, this line stays blank.
The form has one new-address entry. Separate households should each notify the IRS of their own new address.
Line 2 covers more than estate returns. Identify the return before supplying decedent details.
Complete the separate decedent name and personal-number boxes. Keep your own identifying details on line 3; Form 706 instructions use 8822 for an executor’s address change.
Selecting line 2 does not by itself mean a decedent is involved. A gift-return change alone does not require decedent details.
Do not enter an estate EIN or reuse the decedent’s number as your own. Match the existing IRS record and check the official instructions if a personal number is unavailable.
Complete these boxes for Forms 706 or 706-NA; line 3 still identifies you.
First check line 2. Otherwise use the old home mailing address and any special situation listed in the official table.
This lookup is separate from your entries. It does not read the editor, select tax facts or submit the form. Use the old address, not the new one.
Choose the applicable answers to see an address.
Special situations: a foreign country, American Samoa or Puerto Rico; income excluded under section 933; APO/FPO; Forms 2555, 2555-EZ or 4563; dual-status alien; or a non-bona-fide resident of Guam or the Virgin Islands. These are the cases listed in the original table.
Check the complete Where To File table · Page 2The download contains all 2 original pages, including the instructions. Check the entries, complete the applicable signatures and actual dates on paper, and mail separately. FormAgile does not sign or submit the form.
Check your name and personal number, applicable spouse and decedent details, the separate-residence box, each old address and the single new address.
The taxpayer, executor, donor or authorized representative signs as applicable. A spouse generally also signs after a joint return, unless the separate-residence exception applies.
Use the line 2 priority or the old-home-address table above, then check the official instructions. Do not attach this form to your tax return.
Use the applicable taxpayer, spouse or representative signature lines after downloading. The typed title is separate.
Downloading does not sign, mail or submit the change, and does not confirm an IRS address update.
Use Form 8822-B for the mailing address or location of a business or another EIN entity. If home and business details both change, review and prepare the appropriate separate forms.
Read the official form and all instructionsNotify the IRS directly as well. Not every post office forwards government checks, and a postal forwarding request does not replace the IRS address-change process.
Read the official form and all instructionsReceiving your mail does not establish authority to sign. A representative signing for the taxpayer must have appropriate authority and attach a copy of the power of attorney; Form 2848 can be used.
Read the official form and all instructionsYour entries are processed in this browser page. Each form keeps its own draft during site navigation; refreshing or closing the page clears the drafts. Optional analytics, including Clarity recordings, follow your choice in Analytics settings and the Privacy Policy. Download a copy to keep your work.
Yes. The exported PDF preserves all 2 original pages and editable fields. It is unsigned. Follow the recipient’s signing and delivery requirements.
The original PDF has limited field space. If text cannot fit or its characters are unsupported by the PDF font, we will identify the field so you can revise it. We never silently remove characters or clip overflowing content.
The editor uses 8822, revision February 2021, with 2 original pages. Official form text remains in its original language.
8822 · February 2021
FormAgile is an independent service, not affiliated with the IRS or any government agency. Official blank forms are available free from the IRS. This tool does not provide tax or legal advice.