W-8BEN
Foreign individual status · October 2021
Prepare Form W-8BEN to document a foreign individual’s beneficial-owner status and, when applicable, claim income tax treaty benefits. Review the official form and download an editable PDF for your payer or financial institution.
Preparing the official PDF. You can start filling below.
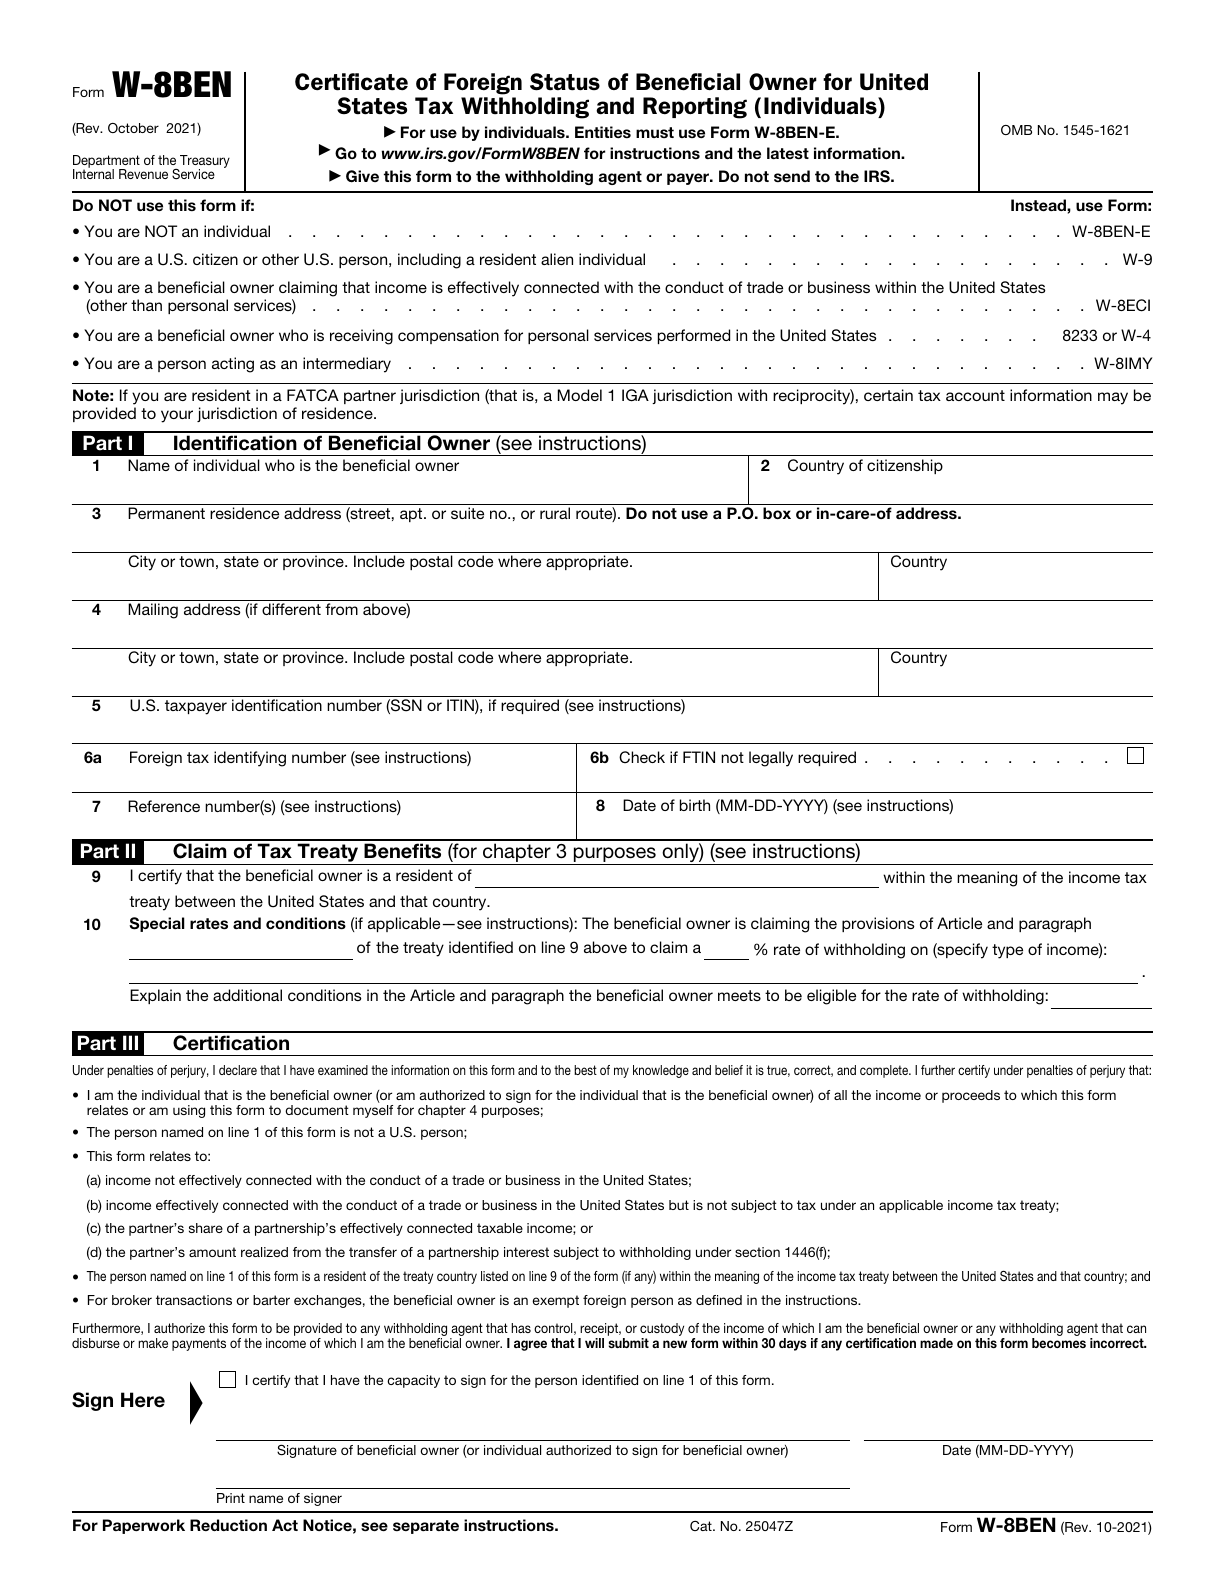
Source: IRS · W-8BEN · October 2021 · Official blank PDF
What to have ready Have the individual’s name, citizenship, permanent residence and any different mailing address ready. Gather U.S. or foreign tax identifiers and birth date when required, requester references, and the treaty article, rate, income type and supporting conditions only if making the relevant claim. Read the official status and income exceptions before deciding this is the right form.
Connect your identity, tax details and treaty claim
W-8BEN documents a foreign individual’s status and, when applicable, a claim for treaty benefits. Read the distinctions below while completing the official form.
Income and identity paperwork travel in different directions
A payer or financial institution may request an individual’s foreign-status documentation. Prepare the form around the individual and the actual request, keeping citizenship, residence and treaty eligibility distinct.
Illustrative cross-border documentation scene; the institution has no fixed country.
Start with the person and the payment
The right form depends on whose status is documented and what the payment represents. A foreign mailing address alone does not establish foreign status.
- Foreign individual → W-8BEN, when applicable
For an eligible individual documenting beneficial ownership, foreign status or an applicable treaty claim. A foreign individual who owns a disregarded entity generally supplies their own details.
- U.S. citizen or other U.S. person → W-9
This includes a U.S. citizen living abroad or holding another citizenship. Tax residency has its own rules; do not decide it from citizenship or a mailing address alone.
Open Form W-9- Foreign entity → review W-8BEN-E or other forms
This editor is for individuals. Foreign entities generally document themselves with W-8BEN-E; intermediaries, trusts and other special cases must follow the specific form-selection instructions.
Check the official form-selection instructions- Services, intermediaries and connected income → check exceptions
U.S. personal-service compensation and intermediary roles may require 8233, W-4 or W-8IMY. Effectively connected income often requires W-8ECI, but treaty-exempt and specified partnership situations require a closer reading of W-8BEN’s certifications.
Check the official form-selection instructions
Use the official selection rules for your circumstances. This explanation does not classify you or your income automatically.
Three country questions, three different meanings
Read each country entry on its own terms. These answers can be different; the editor does not copy one country into another field.
| Official field | What it identifies | How to decide the entry |
|---|---|---|
| Line 2 · Citizenship | Country of citizenship | Use the official dual-citizenship rule when needed. U.S. citizenship directs you to W-9 even if you also have another citizenship. |
| Line 3 · Permanent residence | Address under the tax-residence rules | Use the country where you claim income-tax residence; if none, where you normally reside. Treaty claims and student/researcher cases have specific rules. |
| Line 9 · Treaty residence | Residence within the applicable treaty | Complete only for a treaty claim, using that treaty’s residence requirements. A passport country or mailing address is not enough by itself. |
Keep permanent residence and mail delivery separate
Use a residential address or an accurate local description where streets are not used. Do not use a P.O. box, in-care-of, financial institution or mailing-only address.
Add the separate mailing address only when it differs from line 3. Turning off the separate address clears those entries after confirmation.
Foreign address formats remain free text. A nonresident alien student or researcher claiming an applicable treaty exemption for noncompensatory scholarship or fellowship income may use a U.S. address on line 3 after entry even without a permanent address in the treaty country, if all other treaty conditions are met. On line 9, identify the treaty country where you were resident at or immediately before entry into the United States. This is a specific exception, not a general rule for U.S. addresses.
The form records your certifications. FormAgile does not determine U.S. tax residency, treaty entitlement or a withholding rate.
Choose the tax-ID path that fits the official conditions
Lines 5, 6a and 6b do not ask the same question. A foreign TIN can satisfy some treaty identification requirements, but it does not replace every U.S. TIN requirement.
The original keeps U.S. TIN, FTIN, the legal FTIN exception, references and birth date in separate fields. Their requirements depend on context.
- Line 5 · SSN or ITIN, when required
- Use the individual’s U.S. TIN. Certain partnership and annuity circumstances require it; treaty identification has additional exceptions. Do not put an EIN here.
- Line 6a · FTIN issued by tax residence jurisdiction
- Keep the number’s issued format. The specific U.S.-office financial-account and reportable-income conditions can require an FTIN, subject to the official territory, jurisdiction and legal-obligation exceptions.
- Line 6b · No legal obligation to obtain an FTIN
- This is a declaration under the stated account-holder conditions, including a jurisdiction that does not issue TINs. It is not the same as a number being missing, pending or unknown.
The specified U.S.-office financial-account circumstances can require date of birth on line 8, printed MM-DD-YYYY. A blank line 8 does not alone invalidate the form if the requester already has the date in the account files, or obtains a written statement from the account holder, including by email, associated with this W-8BEN. The editor gives a conditional reminder; ask the requester which documentation applies.
Check the complete line 5–8 instructions with the requester when necessary. The tool checks supported formats, not number ownership or every tax exception.
Part II is a branch, not a required claim
Foreign-status documentation does not itself require claiming a reduced treaty rate. If you do claim, establish treaty residence first, then add special representations only where required.
No treaty claim → leave Part II blank
Complete the other applicable identity and certification sections. You are not required to invent a treaty country or a zero rate to document foreign status.
Claiming treaty benefits → line 9
Enter the country where you meet treaty-residence requirements. Check the actual treaty and your circumstances; nationality alone does not establish entitlement.
Additional treaty representations needed → line 10
Examples include specified royalty claims, students/researchers, business profits or gains not attributable to a permanent establishment, and remittance claims. Many ordinary interest/dividend claims do not need line 10; the actual treaty conditions decide.
If line 10 applies: article and paragraph → rate and income type → additional conditionsFind lines 9–10 on the official W-8BEN
Line 9 identifies treaty residence. Line 10 adds special rates and representations only where the benefit requires them.
No treaty article or rate is selected for you. The explanation field is limited to 90 characters by this product’s readable-layout policy, not an IRS maximum; use a separate statement under the official and requester’s instructions if more is needed.
Read the complete IRS W-8BEN instructionsReview, sign and give it to the requester
The download contains the complete original page, including the preserved blank signature field. Review the certifications, complete an accepted signature and use the actual signature date. Give W-8BEN to the withholding agent, payer or financial institution requesting it, not the IRS. FormAgile does not sign or submit it.
Follow the payment and the form separately
The individual whose status and applicable certifications the form documents.
May be a payer, withholding agent or financial institution; its country is not assumed.
- Income / payment
- Payer to individual: this shows the payment relationship, without determining tax residence, income source, treaty eligibility or a withholding rate.
- W-8BEN documentation
- Individual to requester: after review and an accepted signature, give the form to the party requesting it. Do not send W-8BEN to the IRS.
Citizenship, permanent/tax residence and treaty residence remain separate questions. Neither a foreign passport nor a U.S. location alone chooses the form or a tax benefit; follow the official status and income exceptions.
Check the individual and certifications
Review all entries and read every Part III certification. A draft warning does not confirm the form is valid for your tax circumstances.
Complete an authorized signature
The beneficial owner or relevant account holder, or an agent with legal authority, must sign and date. An agent acting under a power of attorney must include it or a proper copy specifically authorizing this form and should complete the capacity declaration. A printed name or entered date does not sign; FormAgile does not electronically sign.
Give the form to the withholding agent or payer
Give it to the requester, usually the payer or financial institution, before the relevant payment or credit. Do not send it to the IRS. Generally, provide a separate form to each withholding agent.
Review changes and replacement needs
Keep a copy and monitor whether the certified facts remain correct. The general validity period and changes-in-circumstances rules below are different triggers.
Your download keeps the complete original page and the blank signature field. Complete the certification and signing process the requester accepts.
Read all certifications before signing. The original signature field is preserved; filling a name, date or checkbox here does not create a signature.
Validity follows signing and your circumstances
Generally, foreign-status validity runs from signing through the last day of the third succeeding calendar year, unless a change makes the information incorrect. It is not simply three years after downloading.
Some circumstances allow indefinite validity until a change occurs. Chapter 3 and chapter 4 rules differ; check the complete instructions and requester’s requirements instead of assuming one expiration date for every use.
If a change makes a certification incorrect, notify the withholding agent, payer or relevant financial institution within 30 days and provide a new W-8BEN or other appropriate form. Treaty-residence moves and becoming a U.S. person can change the required documentation.
Downloading neither signs nor submits this form. Use the actual signing date, complete any required authorization and follow the requester’s instructions.
Special situations and tool limits
What if I have more than one citizenship?
For line 2, use the country where you are both a citizen and resident when completing the form. If you are not resident in any country where you are a citizen, use the country where you were most recently resident. If you are a U.S. citizen, provide W-9 even if you also hold another citizenship. This entry does not automatically decide your treaty residence.
Read the official form and all instructionsCan effectively connected or partnership income ever involve W-8BEN?
Do not use one blanket rule. Effectively connected income generally calls for W-8ECI, but W-8BEN’s certifications also cover specified treaty-exempt connected income and partnership allocations or transfers. Personal services, intermediaries, hybrid entities and trusts have further form-selection rules. Read the complete official instructions for the actual income and capacity involved.
Read the official form and all instructionsWhat if an account has more than one owner?
The official instructions generally require W-8BEN or W-8BEN-E documentation from all owners to treat jointly owned income or an account as foreign. A W-9 from any joint owner affects how the payer treats the payment and account. Ask the requester what documentation each owner must supply; this editor prepares one individual’s form at a time.
Read the official form and all instructionsHow are my entries handled?
Your entries are processed in this browser page. Each form keeps its own draft during site navigation; refreshing or closing the page clears the drafts. Optional analytics, including Clarity recordings, follow your choice in Analytics settings and the Privacy Policy. Download a copy to keep your work.
Can I edit the downloaded PDF?
Yes. The exported PDF preserves the original page and editable fields. It is unsigned. Follow the recipient’s signing and delivery requirements.
Why might some text need review?
The original PDF has limited field space. If text cannot fit or its characters are unsupported by the PDF font, we will identify the field so you can revise it. We never silently remove characters or clip overflowing content.
Check the original W-8BEN and complete instructions
This guide is tied to the October 2021 original. The separate IRS instructions explain account, income, residence, treaty and signer exceptions in full.
W-8BEN · October 2021
FormAgile is an independent service, not affiliated with the IRS or any government agency. Official blank forms are available free from the IRS. This tool does not provide tax or legal advice.